Can You Get a Mortgage on a Small Cabin?
You can price the lumber, the windows and the roof. What surprises people is that a bank may not lend on the finished building at all, and that nobody warned them before they bought the land.
Small cabins are hard to finance through a normal mortgage for three reasons: they often have no comparable sales nearby, they frequently have non standard water, waste or heating, and lenders treat a seasonal or unpermitted structure as a different kind of risk.
What makes a lender say no
- No permit. This is the big one. Appraisers routinely assign unpermitted square footage no value, which means the building you just spent money on does not exist on paper.
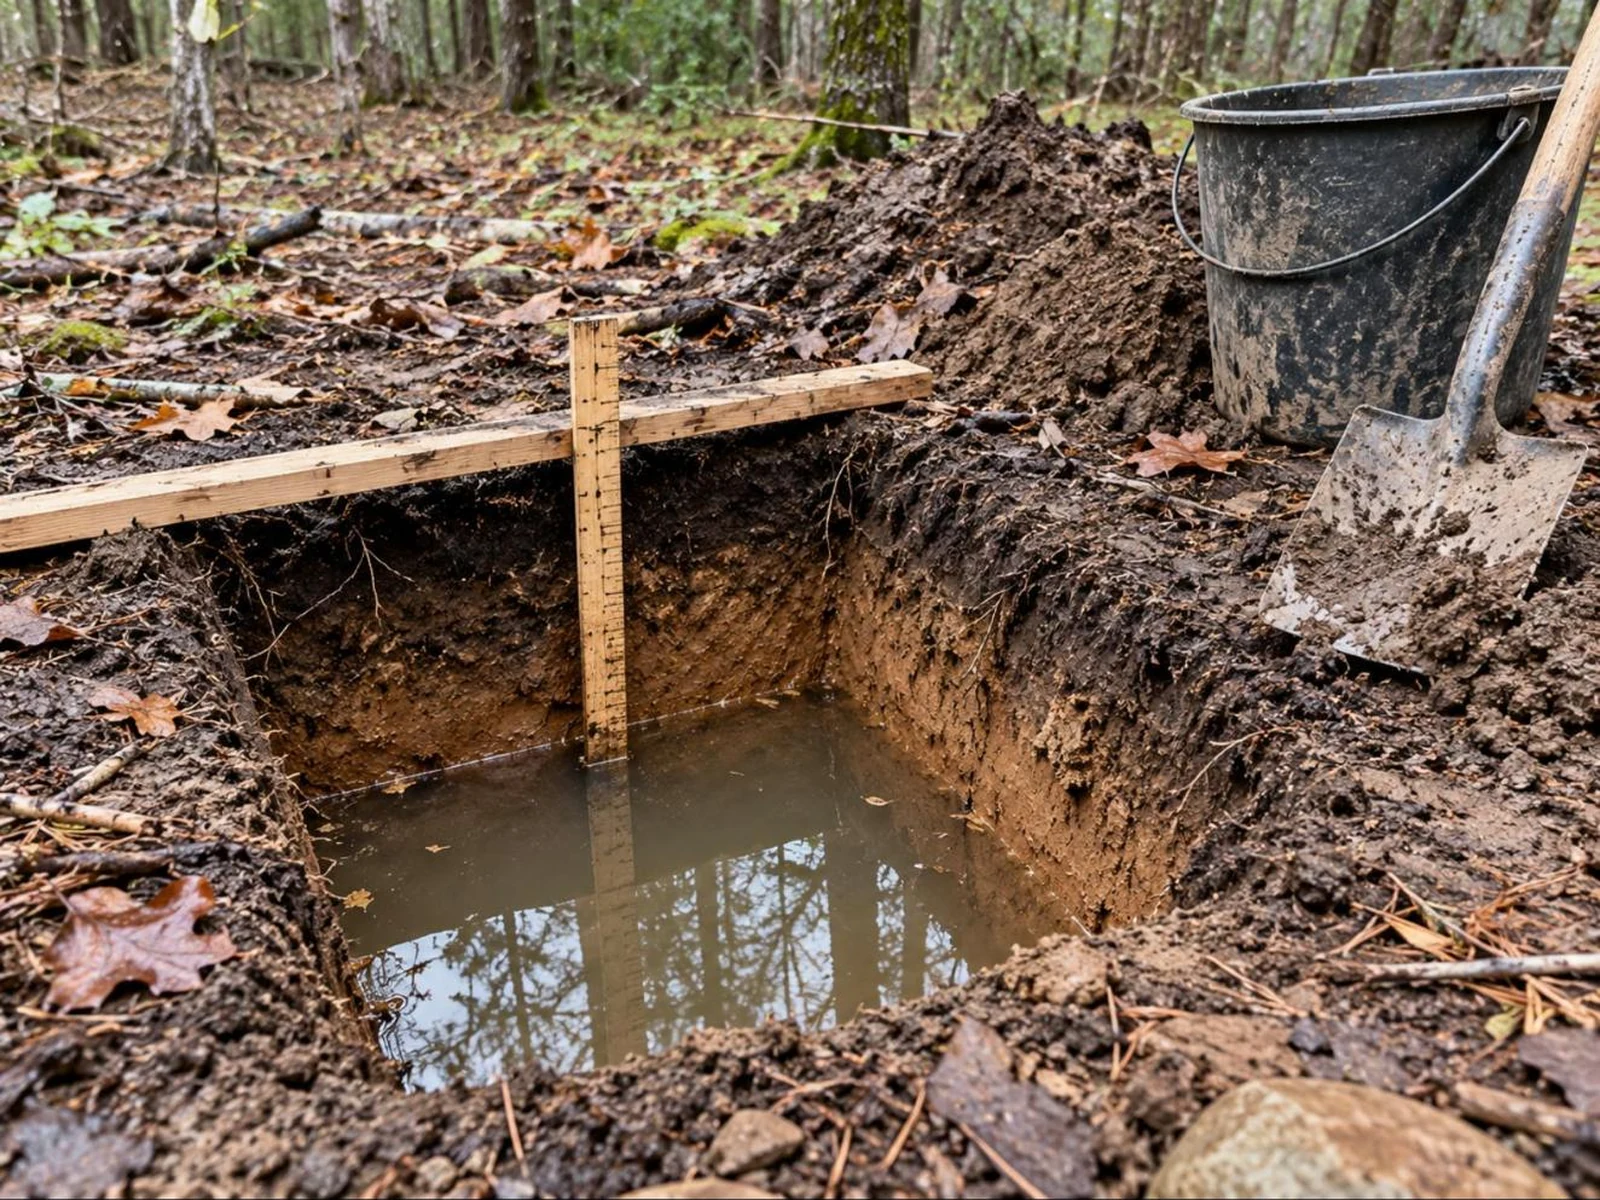
- Water supply. Most lenders want public water or a permitted, tested well. A creek, a spring or a hauled tank is usually declined.
- Waste. An approved septic system or a sewer connection. A composting toilet alone is often not accepted.
- Heat. Many lenders want a permanent heat source that is not solely a wood stove.
- Access and address. Year round legal access and a recognised postal address. A seasonal track can be a problem.
- Comparables. An appraiser needs recent sales of similar properties. In rural counties there may not be any.
The routes that actually work
Cash out refinance on your main home
The most common path owner builders report. You borrow against a property the bank already understands and pay for the cabin in cash. It avoids every problem above.
A local bank or credit union
Small lenders who keep loans on their own books can lend on property that a national underwriter would decline, because they know the area and are not selling the loan on. Expect a larger deposit, a shorter term and a higher rate. This is the single most useful call to make.
Land loan plus owner financing
Finance the land conventionally and have the seller carry part of the balance, with the structure valued near zero until it is complete and permitted.
Construction to permanent loan
Available for permitted builds with licensed contractors and a full plan set. It converts to a normal mortgage at completion. The paperwork is heavier and the plan set has to be complete and costed, which is another reason to buy a set with a material list.
Three things that protect your options
- Permit everything. It is the difference between an asset and a liability.
- Install a permitted well and an approved septic system even if you plan to live simply. They are what makes the property financeable and insurable.
- Keep the paperwork. Permit, inspection records, the plan set, invoices. An appraiser and an insurer will both ask.
Insurance is the quieter problem
Insurers ask the same questions as lenders and add their own: how far is the nearest fire service, is the building occupied seasonally, is there a wood burning appliance and was it installed to code. An unpermitted cabin can be refused cover entirely, and a claim on one can be denied after the fact. The federal consumer finance regulator’s home buying guidance is a reasonable neutral starting point for understanding what underwriters look at.
Plan the money before the design
If you intend to finance the build rather than pay cash, talk to a local lender before you buy a plan. Their requirements shape your well, septic, heating and permit decisions, and all four are cheaper to decide early. Our cabin permit guide covers the approval order, and the cost breakdown covers what the build itself runs.
FAQ
Can you get a mortgage on a small cabin?
Yes, if it is permitted, has an approved water supply and septic system, a permanent heat source, year round access and there are comparable sales nearby. Where one of those is missing, a local bank portfolio loan is usually the realistic route.
Will a bank finance an off grid cabin?
Most national lenders will not, mainly because of water supply and heating requirements. Local lenders sometimes will, with a larger deposit.
What is an unpermitted cabin worth to an appraiser?
Often nothing. The land may be valued normally while the structure is excluded, which can leave a buyer financing far less than they expected.
Does a composting toilet affect financing?
It can. Many lenders want an approved septic system or sewer connection regardless of what fixtures you install. Check with your health department and your lender before you decide.
Complete plan sets, $99, nothing held back
Every plan lists its sheets, room dimensions and build cost range before you pay. Floor plans, elevations, section, foundation, framing, electrical, plumbing and a material list, delivered as a print ready PDF the moment you check out.